Since 1 August, Portuguese buyers can borrow less. Think that is just a banking matter? It is also about how you communicate value. What changed, and five strategic responses.
Since 1 August 2026, buying a home in Portugal with a mortgage has become harder for a significant share of buyers.
Not because of property prices. Because of the rules that set how much a bank can lend.
Banco de Portugal revised its Macroprudential Recommendation for new credit agreements, and from that date creditworthiness assessments follow stricter criteria. The practical effect is easy to grasp: for the same income, many households will be approved for less credit than they could get in July.
This is not a crisis. It is not a market collapse. But it is a real change of context. Developers, builders and architects who understand what it means in practice will have an edge over those who ignore it.
Mortgages in 2026: what exactly changed on 1 August
To avoid inaccuracies, it is worth starting with the facts, without interpretation.
The maximum recommended debt-service-to-income ratio (DSTI) fell from 50% to 45%. This measures what share of a household's net monthly income can go on the repayments of all its loans: the new mortgage plus any existing credit. With a lower ceiling, banks have less room to approve loans for households whose repayments already take a large share of their income.
Loan-to-value limits (LTV) are unchanged. They remain 90% for a main residence and 80% for other purposes.
The special regime of 100% financing for banks' own properties has gone. These properties, which come from loan recovery processes, are now subject to the general 90% limit, which may require buyers to put in more of their own capital in these specific cases.
Terms have become more flexible for younger buyers. Borrowers aged 30 to 35 can now take out loans of up to 40 years, instead of the previous 37. The rule limiting the average maturity of each bank's whole portfolio to 30 years has also been removed; that rule was aimed at banks' overall management, not at each client's individual term.
One nuance is rarely communicated clearly: this is a macroprudential recommendation, not a law. Banks must follow it or justify to Banco de Portugal the cases where they depart from it, and they may, within limits, approve up to 10% of new contracts outside these criteria. So the rules do not prevent lending above the limits, but they make it rarer and more dependent on each institution's risk profile.
What this means in practice: buyers with little headroom, with other loans running, or with incomes close to the limit will feel this change directly. They will be able to borrow less, will take longer to decide and will need more confidence before going ahead.
Why this matters for sellers, not just buyers
When credit tightens, there is a natural temptation to think the answer is simply to wait for it to pass, or to cut prices to make up for buyers' lower borrowing capacity.
I have written before about why that second answer is rarely the best. This moment is no exception.
When access to credit tightens, what changes is not only how much the buyer can pay. It is also how they decide.
A buyer with less financial room naturally becomes more cautious. They take longer. They visit more projects before deciding. They need to feel more confident before making a reservation, because the perceived risk of getting it wrong is higher when the financial cushion is smaller.
That means projects that communicate value clearly, reduce uncertainty and build the buyer's confidence faster will have a disproportionate advantage in this context. And those that depend on repeated physical visits, generic sales material or unclear arguments will feel the slowdown more sharply.
What to do: five strategic responses
1. Reduce the number of decisions the buyer has to make "blind"
The less financial room a buyer has, the less willing they are to commit on the strength of floor plans, descriptions and imagination.
That makes immersive 3D renders, virtual tours that let buyers explore the property before any physical visit, and visualisations that answer doubts before they become objections more important than ever.
Every doubt left unresolved before the sales meeting is a reason to postpone the decision. And postponing, in a more cautious market, often means losing the buyer to another project.
2. Communicate the total cost of ownership, not just the purchase price
With less financing available, buyers pay more attention to what the home will cost to run, not only to what it costs to buy.
This is a direct opportunity for projects with an energy-efficiency component. A home with a high energy rating costs significantly less to run over time, and with tighter credit that monthly saving can be the argument that makes the difference between a repayment that fits the budget and one that does not.
Communicating this clearly and tangibly (not in technical coefficients but in euros saved per month) turns energy efficiency from a "nice extra" into a "deciding factor for bank approval".
3. Back functional, moderately sized unit types
The latest market data already point to growing demand for one- and two-bedroom homes: more affordable, easier to finance within the new limits and more in line with the real purchasing power of those entering the market now.
For developers with projects still at design stage, this is a signal to consider. For those already marketing developments, it is a communication argument: showing how smaller units can be designed not to feel small, with efficient layouts, well-handled light and storage that maximises the sense of space.
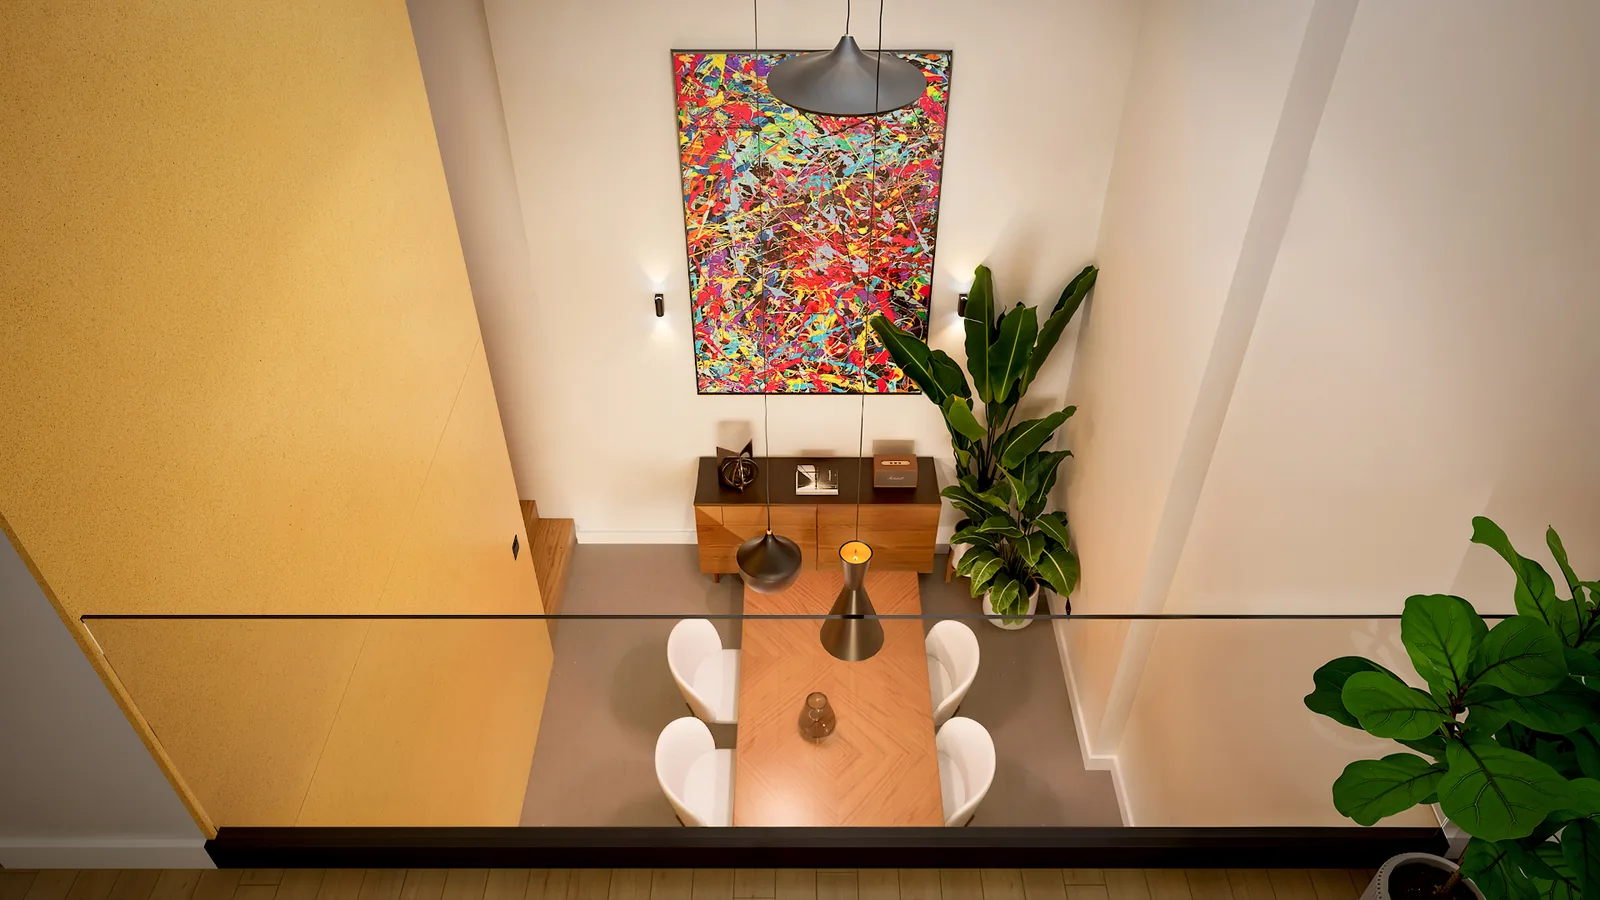
3D visualisation has a specific role here: a good render can make a well-designed one-bedroom flat look generous and complete, which is exactly the argument this market moment calls for.
4. Work with mortgage brokers from the marketing stage
According to recent Banco de Portugal data, credit intermediaries have become the main channel for taking out mortgages in Portugal. That means many clients' buying journey goes through a conversation about financing earlier and earlier.
Developers who build this into their sales strategy, offering credit simulations adjusted to the new rules or working with trusted brokers from the pre-launch stage, remove a significant source of uncertainty from the buyer's decision.
The sooner a buyer knows, with confidence, that they can finance the property they are considering, the faster the decision moves.
5. Do not compete on price, compete on clarity
This is the most important point of all, and the one that ties everything else together.
In a market where buyers objectively have less financial room, the temptation to cut prices to compensate is strong. But a buyer with less borrowing capacity is not necessarily looking for the lowest price; they are looking for the safest decision.
Projects that communicate value clearly, through images that remove doubt, arguments that answer real concerns and a buying experience that conveys confidence, do not compete on price. They compete on peace of mind.
And in a more cautious market, peace of mind is worth more than a discount.
What this means for the coming months
The new rules apply to creditworthiness assessments carried out from 1 August 2026. Applications assessed by 31 July remain under the previous rules, even if the contract is signed later, so the full effect of this change will only be felt in the market over the coming months, as new mortgage applications follow the revised criteria.
For developers with launches planned for the autumn, now is the right time to adjust the communication strategy, before the competition grasps the scale of the change and reacts.
For architects and builders, it is a chance to position projects and proposals as smart answers to a market that is, objectively, asking for more efficiency, more clarity and less room for doubt.
Conclusion
Tighter credit is not bad news dressed up as good news. It is simply a change of context, and like every change of context it creates an advantage for those who adapt first.
Buyers have not disappeared. They still want to buy a home. But they will decide more carefully, with a greater need for confidence and less room for the risk of getting it wrong.
Projects that meet that need, with clear communication, visualisation that removes doubt and well-built value arguments, will not just get through this moment.
They will stand out in it.
👉 Preparing a project for the coming months and want to make sure the communication fits this new market context? Talk to us.
Foreseen Projects (formerly Hugo Guerra Design) is a studio specialising in architectural and real estate 3D visualisation, a strategic partner to architects, developers, builders and interior designers in Portugal.